
GEORGIA HOME FINANCING
Every Way To Finance A Home.
One Person Who Explains All Of Them.
One 15-minute conversation with Teala and you will know exactly which path fits your home, your numbers, and your timeline. Plain answers, no jargon, no runaround.
No credit pull · 15 minutes · Straight answers
Situation Navigator
Find Yourself In 10 Seconds.
Tap the row that sounds like you. I'll take it from there.
Don't see yourself here? Call me and we'll find the right fit: no pressure, no jargon.
THE HOME PURCHASE JOURNEY
Begin Your Legacy
Buying a home in North Georgia should feel like a clear next chapter, not a guessing game. Before you set foot in a single showing, we map the numbers that actually decide your offer: what you can comfortably afford, what the monthly payment looks like at today's rate, and what cash you need at the closing table.
- Pre-approval clarity before you tour a single property
- A local pricing read on the counties you are actually shopping
- Down payment and closing cost figures mapped up front
- One advisor walking with you from first call to closing table
Refinancing Paths
Optimize Your Equity
Equity can be protected or put to work. The right path depends on whether your goal is a lower carrying cost or access to capital you have already earned.
Rate-and-Term Refinance
A straight swap: you keep the same principal and change only the cost of carrying it.
- Trades your current rate and term for stronger ones, with no new balance added.
- Best suited to borrowers who want a lower payment or a shorter payoff window.
- Your equity position stays exactly where it is today.
Cash-Out Refinance
You borrow against the appreciation you have already earned and take the difference in hand.
- Converts a portion of your equity into usable capital at closing.
- Commonly used for renovations, consolidating higher-rate debt, or a future purchase.
- Your loan balance rises, so the return on that capital has to justify it.

Spousal & Co-Owner Buyouts
Navigate Forward with
Clarity
When a marriage ends or a business partnership changes, the home you shared should not become another point of conflict. We structure co-owner buyouts that let one party stay in place while the other walks away with their equity in hand.
- Buyout funded in as few as 10 business days
- Cash-out refinance or buyout financing sized to your agreement
- One documented settlement figure, agreed before closing
- Discreet, private handling from application through funding
No obligation. Every conversation is confidential.
Second Homes in North Georgia
Your Mountain Escape
Awaits
A porch that faces the sunrise, a gravel road that ends at your own front door, and cool air in July. A second home in the Blue Ridge foothills is a different kind of purchase, and it is underwritten differently too. We finance cabins, lake houses, and ridge-top retreats across Blue Ridge, Ellijay, Dahlonega, and Blairsville, and we know which programs treat your mountain place as a home rather than a rental portfolio.
- Second-home financing for cabins, lake homes, and mountain retreats
- Street-level knowledge of Blue Ridge, Ellijay, Dahlonega, and Blairsville pricing
- Clear guidance on second-home versus investment-property underwriting
No credit pull to start. A real person on the phone within one business day.
DSCR LENDING FOR INVESTORS
Scale Your Portfolio
DSCR underwriting focuses on the property's rent roll, not your W-2. Qualify with market rents and signed leases while keeping personal income out of the file and capital free for the next acquisition.
- Qualify on rental income: no personal income verification or tax returns
- Target 1.00x DSCR or higher for durable monthly cash flow
- Investor-focused terms for single-asset and portfolio loans
- Entity vesting and asset-first underwriting built for speed
1.00x+
MINIMUM DSCR
30-Year
FIXED TERMS
Rental
INCOME BASIS
The Offer
The Clear To Close Plan
Whichever loan you need, you get the same plan. It costs $0 to start.
No credit pull. No obligation. Just your real numbers in plain English.
Every loan. One plan.
Here is exactly what you get, from first call to closing day:
- $0 to start. Your numbers, your scenario, and your written plan cost nothing up front.
- One point of contact: Teala. The same person answers the phone from first call to closing day.
- Real numbers, in writing. Actual rate, actual fees, actual cash to close, before you commit.
- Zero jargon. Every line item explained in plain English, not loan-officer shorthand.
- Speed where it counts. Pre-approval letters turned around in hours, not weeks.
- Every loan under one roof. Purchase, refinance, buyout, second home, and DSCR, so you never restart the process.
- Clear to Close means something. Your file is fully documented and underwritten before we lock and move.
Same team, same plan, same standard: purchase, refinance, buyout, second home, and DSCR.
SIDE BY SIDE
Compare Your Options
Six financing paths, one clear view. Compare how each solution is priced, who it is built for, and what it takes to qualify before you commit.
| Solution | Buying a Home | Refinancing | Spousal Buyout | Mountain & Second Homes | DSCR Investors | Clear to Close Plan |
|---|---|---|---|---|---|---|
| Rate type | Fixed and adjustable, owner-occupied pricing | Rate-and-term or cash-out, fixed and ARM | Fixed-rate purchase with equity buyout | Second-home pricing, fixed and ARM | Asset-based pricing, no income verification | Locked rate with a committed closing date |
| Best for | First-time and move-up buyers ready to purchase | Homeowners lowering payments or accessing equity | Separating spouses transferring property ownership | Buyers of cabins, retreats and second residences | Investors qualifying on rental income | Buyers who need certainty on rate and timing |
| Typical requirements | Credit, income and down payment documentation | Existing equity and current mortgage history | Separation agreement and property appraisal | Primary residence plus second-home reserves | Lease agreement and DSCR of 1.0 or higher | Pre-approval before the plan is issued |
| Time to close | 30 to 45 days | 3 to 6 weeks, appraisal included | 4 to 6 weeks with legal review | 35 to 50 days, appraisal dependent | 30 to 45 days once the property is leased | Accelerated path with milestone tracking |
Illustrative summary for comparison only. Final rates, terms and eligibility are confirmed during underwriting.
THE DETAILS, MADE CLEAR
Answers to Your
Questions
You should not need a finance degree to understand your options. These are the questions we hear most often from buyers and homeowners across North Georgia, answered in plain language.
Licensed in Georgia and North Carolina. No obligation.
What documents do I need to get started?
Most files begin with the last two years of tax returns, your two most recent pay stubs, two months of bank statements, and a copy of your government-issued ID. If you are self-employed or purchasing an investment property, we may need a little more, but we request it as one clear list rather than piecemeal.
How long does the process usually take?
From a completed application to a clear to close, most files land in the three to four week range, and a pre-approval can often be issued within a single business day. Timelines stretch when documents arrive slowly or an appraisal runs long, so early and complete paperwork keeps things moving.
What credit score do I need to qualify?
There is no single threshold, because the right answer depends on the structure you choose. Stronger credit opens more competitive pricing, and some scenarios can work with scores in the 600s. We look at the full picture rather than one number and tell you plainly which structures fit.
Should I work with a broker instead of my bank?
A bank can only present its own products. We place your file with the lender whose guidelines actually match your situation, which matters most when income is complex, the property is unusual, or the timeline is tight. You keep one point of contact and one set of explanations through closing.
Can I lock my rate and keep watching the market?
Rate locks become available once we have a complete picture of your scenario. We walk you through the length of the lock, what it costs, and what happens if closing is delayed. If rates move, we review whether a float down option is worth the trade off before your lock expires.
What are closing costs and who pays them?
Closing costs typically run between two and five percent of the loan amount and cover lender fees, title work, recording, and prepaid items such as taxes and insurance. Your closing disclosure itemizes every line, and we review it with you before you sign so nothing is a surprise on the final day.
LET'S GET STARTED
Ready to Get Your
Numbers?
Share a few details and a mortgage advisor will call you with real numbers, not guesses.
Pre-qualification takes about 5 minutes. No obligation, and no hard credit pull.
Get My Numbers is a licensed mortgage brokerage. All loans are subject to credit approval; rates, terms, and program availability vary by state and may change without notice. This is not a commitment to lend. Equal Housing Opportunity.
Teala · Georgia Mortgage Expertise
Every Way To
Finance A Home
Buying your first place, refinancing, navigating a divorce buyout, or funding a rental property: Teala structures the loan around your life, not a call-center script.
No credit pull to see your numbers · Straight answers in 15 minutes
Quiet Orientation
Find Yourself In
10 Seconds
Scan the left column until something sounds like you. Your answer is on the same line.
If you want to
Your solution
Next step
Buy your first home
First-time buyer pre-approval, explained in plain English.
Lower your monthly payment
Refinance options laid side by side, so the trade-offs are visible.
Exit a buyout or divorce
Buyout refinance with the numbers written down, not implied.
Buy a mountain or second home
Mountain home lending reviewed by someone who lives here.
Buy an investment property
DSCR investor loans qualified on the property, not your tax returns.
Win a competitive offer
A clear-to-close plan built before you start shopping.
Don't see yourself? Call me and we'll map it out together in one short conversation.
For Greater Atlanta Buyers
Make An Offer The Seller
Takes Seriously
First-time and move-up buyers across Greater Atlanta who want a lender whose pre-approval actually holds up when it matters, in a market where the best homes take offers in days, not weeks.
What Usually Goes Wrong
A pre-approval that was really just a rate quote. An underwriter who goes quiet for a week while the seller takes someone else's offer. A closing date that slides past the contract deadline and puts your earnest money at risk.
How I Fix It
- A fully underwritten pre-approval, not an estimate: you shop with the confidence of a cash buyer.
- Income, assets and documents verified before we write the offer, so nothing surfaces on day 25.
- One direct line from first call to keys: you work with me, never a call center.
- Weekly milestone updates shared with your agent, so nobody has to guess where we stand.
- Georgia contracts, HOA quirks and appraisal timelines handled by someone who sees them every week.
No obligation. Takes about 15 minutes to get started.
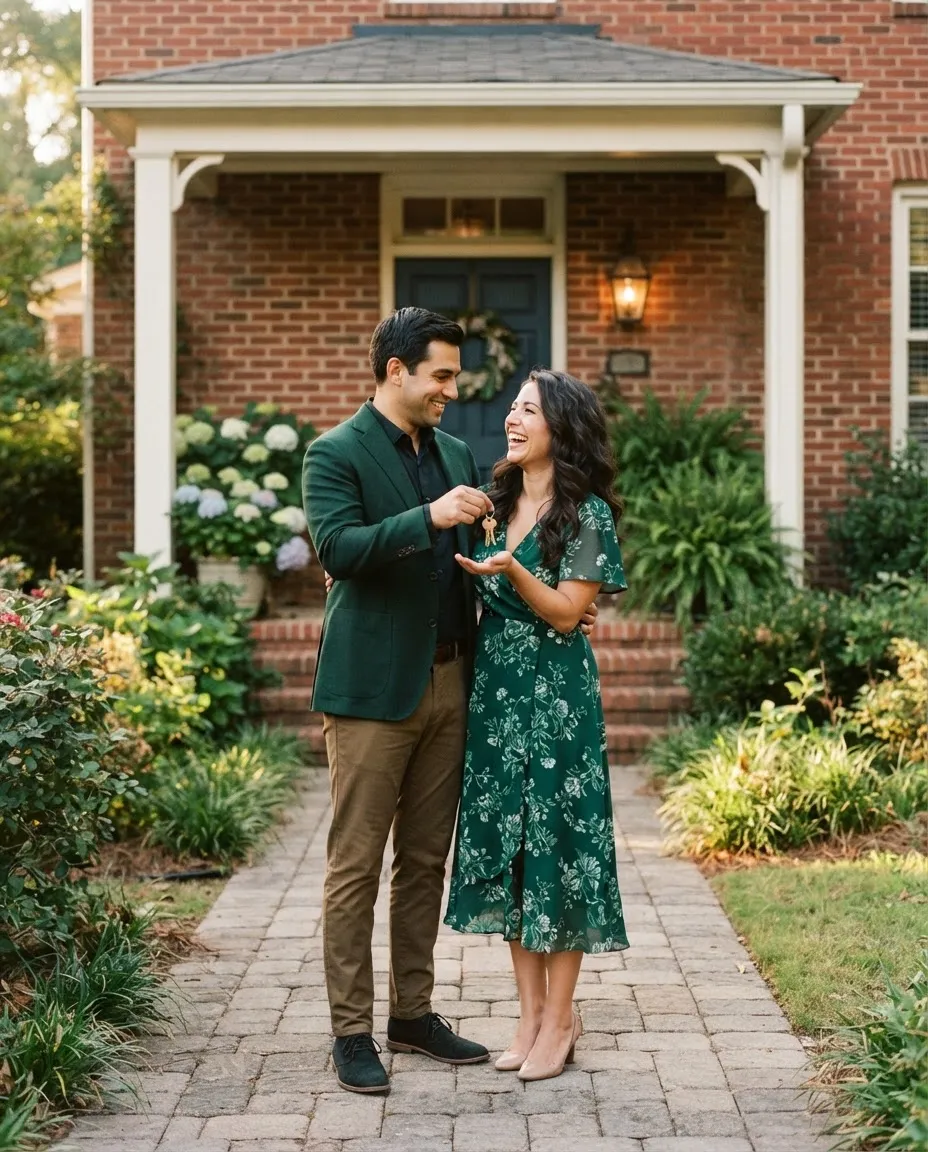
Divorce & Inheritance Buyouts
Keep The House.
Buy Out The Other Owner
For families in divorce or inheritance: one owner keeps the home, the other is paid out. The mortgage has to be rebuilt for a single borrower, on terms the court, the attorney and every lienholder will accept.
How It Works
01 Pre-Settlement Analysis
We model the buyout before the settlement is final: valuation, each party's borrowing power, and what every option actually costs.
02 Court-Ready Valuation
Payoff figures, liens and title work reconciled into one file your attorney and the court can rely on.
03 Single-Borrower Close
The refinance closes in the remaining owner's name, the departing owner is paid, and title transfers cleanly with no loose ends.
Why It Can Cost Less
- A pre-settlement analysis prices the buyout before anyone signs, so there is no renegotiation later
- Assets awarded in the settlement can count toward reserves, lowering the loan amount you need
- One borrower, one loan file: fewer underwriting passes and less in closing costs
We work alongside family law attorneys and estate counsel. Ask for a pre-settlement mortgage analysis before your next mediation.
North Georgia Specialist
A Mountain Place Without
The Paperwork
Second homes in the Blue Ridge foothills are financed differently from anything in the metro. Log walls, private wells, and septic fields change what a lender can accept. We underwrite those details on day one, not after an appraisal comes back short.
- Log and timber construction: specialty appraisal comparables and carriers that actually insure them
- Private wells and spring-fed water: documented flow and potability tests that clear underwriting
- Septic systems and perc results: verified before your file reaches the closer
- Gravel access, shared roads, and recorded easements: title work handled up front
The rule to know: a mountain property has to justify its own value. If the acreage, the well, or the log construction will not support the appraisal, the loan stalls no matter how strong your file looks. We run those checks before you pay for an appraisal, so a surprise never lands on closing week.
No credit pull to start. We review the property first.
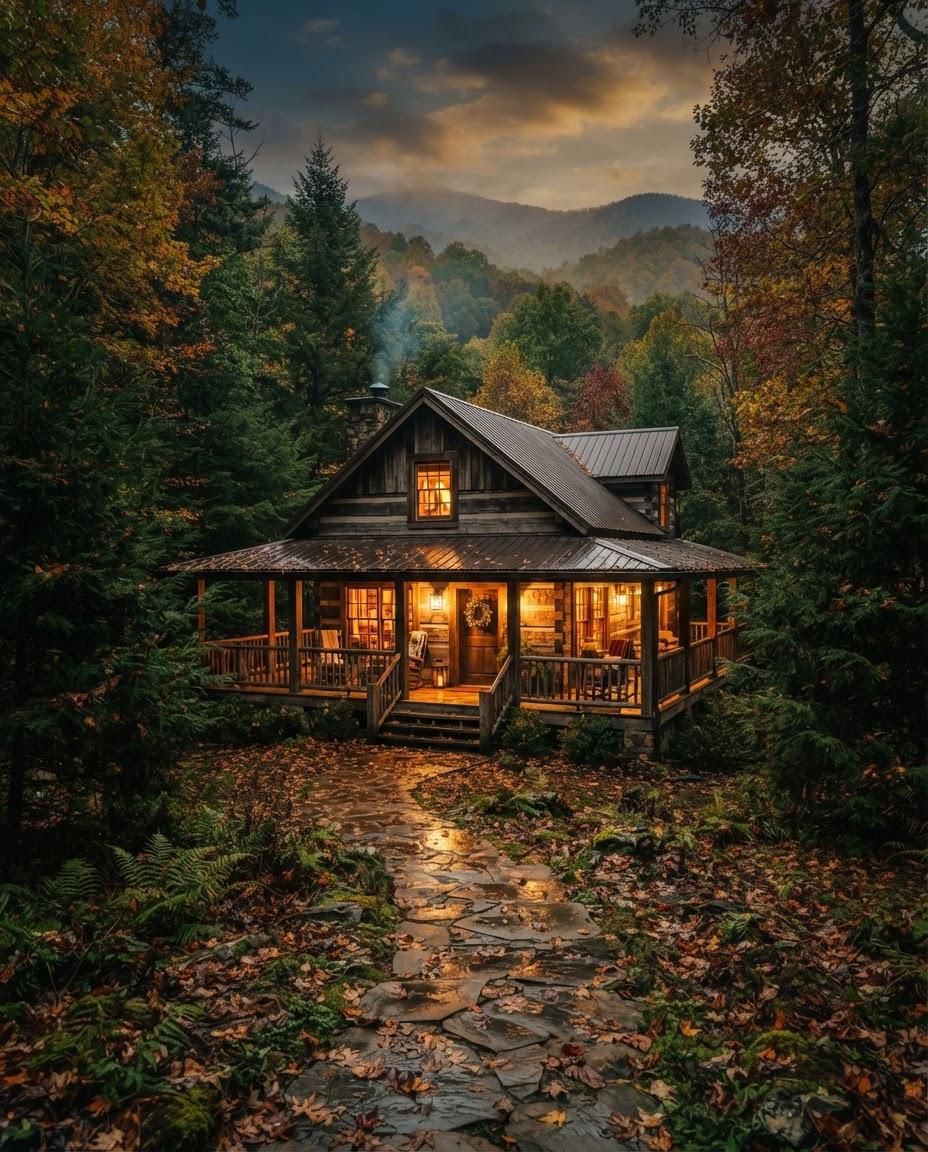
Blue Ridge, GA: log home on private well and septic
Business-Purpose Loans
Qualify On Rent, Not
Tax Returns
Who It's For
You are buying a 1 to 4 unit rental, a short-term rental, or a small portfolio property held in an LLC. The property's own rent has to carry the loan: not your W-2, and not a two-year average of write-offs.
What Usually Goes Wrong
A strong rental year can still fail a conventional file. Depreciation, repairs, and mileage write-offs shrink reported income, so the debt-to-income math says no while the property cash-flows. Add an appraised rent below contract rent and the file stalls at the last step.
Guideline Snapshot
Term
Detail
Income Basis
Lease rent and appraiser market rent (1007). Tax returns are not the qualifying document.
DSCR Minimum
1.00x to start. 1.25x or better earns the cleanest rate and pricing.
Credit Floor
620 minimum. 700+ improves leverage and reduces reserve strain.
Down Payment
20% to 25%. A larger down payment clears a tight rent-to-payment ratio.
Reserves
3 to 6 months of PITIA, stepped up on low-DSCR or multi-unit files.
Borrower Entity
LLC or corporation vesting allowed. No personal debt-to-income calculation.
Property Types
1 to 4 unit residential, warrantable condos, and short-term rentals in eligible markets.
Business-purpose loans only. Not for primary residence or second-home occupancy.
Quick Reference
All Six Solutions
Side By Side
Every program we write, in one place: who it fits, what underwriters weigh, and the single detail that decides the outcome.
| Solution | Best For | Qualifies Mainly On | The One Thing To Know |
|---|---|---|---|
| Home Purchase | First-time buyers and move-up families actively making offers | Income, assets, credit score, and a fully documented loan file | A verified pre-approval carries more weight with sellers than a pre-qualification. |
| Refinance | Owners cutting a rate, shortening a term, or turning equity into cash | Available equity, credit history, and twelve months of clean payments | Cash-out restarts the clock on your term. Rate-term does not. |
| Divorce Buyout | One spouse keeping the house after a separation or divorce | Solo income, equity position, and a signed settlement agreement | The new loan has to release the departing spouse from the note, not just the deed. |
| Mountain And Resort | Cabins, second homes, and properties in resort or rural areas | Property appraisal, reserve funds, and second-home occupancy rules | Rental income only counts when the program allows it, so plan reserves without it. |
| DSCR Investor | Investors buying or refinancing a rental property | The rent the property earns against its mortgage payment | A ratio under 1.0 usually means a larger down payment, not a denial. |
| Clear To Close | Buyers under contract who need the fastest possible funding | A complete file, reviewed and underwritten before the offer | The speed comes from underwriting first, not from rushing the closing. |
Guidelines above are general. Final qualification depends on the complete file and current program rules.
Not sure which line describes your situation? Answer two quick questions and we will point you to the right program.
STILL NOT SURE?
Your Questions,
Answered.
A mortgage decision should never feel like a gamble. If you are unsure how your credit, your timeline, or a quote you already have fits into the picture, bring the question here. We will walk through it plainly, with no pressure and nothing hidden in the fine print.
No credit pull to start. No obligation to proceed.
Will my credit score hold me back?
Often, no. We work with a wide range of credit profiles, and a lower score usually changes the shape of the loan rather than the possibility of one. If there is something worth improving first, we tell you exactly what and roughly how long it takes, so nothing catches you by surprise later.
How long does this take from start to closing?
Most files move from first conversation to clear-to-close in three to five weeks. If you are buying on a fixed closing date, we work backward from that date and tell you honestly whether it is realistic. We would rather set a timeline you can plan around than a promise we have to walk back.
I already have a quote. Why would I look again?
Because a second look costs you nothing and frequently saves you something. Send the Loan Estimate you already have and we will review it side by side with ours, line by line, including the parts that are easy to bury. If your current quote genuinely holds up, we will say so and you keep it with confidence instead of doubt.
What do I actually need to get started?
A rough picture of the property, a sense of your income, and what you want the loan to accomplish. Documents come later. The first conversation is about your situation, not paperwork.
Can I qualify if I am self-employed or own a business?
Usually yes. We are comfortable reading business returns, K-1s, and bank statements rather than only W-2s. Expect a few extra questions about how your income is structured, and we will handle the rest from there.
What if my situation changes partway through?
Tell us early and we adjust. A job change, a gift, a large deposit, or a new debt can all be worked with if we know before closing week. Silence is the only thing that genuinely creates problems.
Your Next Step
You Don't Need To Know Which Loan You Need.
You Need 15 Minutes.
One short call is all it takes. I'll look at your goals, your numbers, and the loan options that actually fit, then hand you real figures to compare. No paperwork marathon, no pressure.
Or call me now: (305) 778-9571
Average time to close is 21 to 30 days from application, and timelines vary by lender, property type, and documentation. Rates and terms are subject to underwriting approval. This is not a commitment to lend.
Teala - Ameris Bank
Mortgage guidance for Marietta, the North Georgia mountains, and investors statewide. Personal service, clear numbers, no guesswork.
Marietta Office
Ameris Bank Mortgage
125 Roswell Street, Suite 200
Marietta, GA 30060
Office hours: Monday - Friday, 9:00am - 5:00pm ET
Licensing & Disclosures
Teala, Mortgage Loan Originator - NMLS #1234567. Ameris Bank - NMLS #1234567. Licensed in Georgia. Branch office: 125 Roswell Street, Suite 200, Marietta, GA 30060. NMLS Consumer Access: www.nmlsconsumeraccess.org
All loans are subject to credit and property approval, program guidelines, and applicable underwriting criteria. Rates, fees, and terms are subject to change without notice. This is not a commitment to lend. Pre-qualification is not a loan approval, and final approval is contingent on verification of all borrower and property information. Additional restrictions and conditions may apply. Equal Housing Opportunity.


© 2026 Teala - Ameris Bank. All rights reserved. Ameris Bank is an Equal Housing Lender. Member FDIC.
PURCHASE LOANS & PRE-APPROVAL
Make An Offer The Seller Takes Seriously.
A pre-approval that holds up under scrutiny is the difference between a serious offer and a rejected one. Here is how I structure yours, before you ever walk into a showing.
16-DAY AVERAGE CLOSE
From accepted offer to clear-to-close on purchase loans I structure, underwrite, and carry to the finish line myself.
Who it's for: First-time buyers, move-up buyers, and anyone competing in a market where the best homes draw multiple offers within days.
What usually goes wrong: Buyers get pre-approved online in minutes, then lose the home because the letter was never underwritten, the timeline was never real, or the lender went silent the moment the seller's agent called.
How I Fix It
- An underwritten pre-approval, not a soft online estimate: sellers and their agents see verified income, assets, and credit up front.
- A 16-day average close, so your offer timeline stands next to cash and wins.
- Direct access to me by phone, including nights and weekends. No call center, no waiting on hold.
- Every document reviewed before we write the offer, so nothing surfaces in underwriting and puts your closing date at risk.
Loan Types
Conventional, FHA, VA, Jumbo, and USDA purchase loans, plus physician and professional programs built for the way you actually earn.
REFINANCING OPTIONS
Refinancing On Your Terms
There are two ways to use the equity in your home, and neither one is automatically the right move. Here is how each works, what it costs, and how to tell whether it pays off for you.
OPTION 01 - RATE-AND-TERM
Change Your Rate, Your Term, Or Both
You replace your current loan with a new one at a different rate, a different term, or both. The monthly payment changes. The balance you owe does not go up, and no cash comes out at closing.
- Set your current payoff beside the new loan estimate
- Divide total closing costs by your monthly savings
- That month count is your break-even: past it, you are ahead
Break-even in plain numbers: $4,800 in closing costs against $150 a month saved means you are even in 32 months. Stay in the home longer than that and the refi has paid for itself.
Soft credit pull only. No obligation to proceed.
OPTION 02 - CASH-OUT
Turn Equity Into Cash Without Selling
Cash-out replaces your mortgage with a larger loan and hands you the difference in cash. The equity you built becomes spendable, and your home now secures the full new balance.
- Your loan balance rises by the amount you take out
- Closing costs apply to the whole new loan, not just the cash portion
- A higher balance leaves less cushion if values soften later
Where it earns its keep: consolidating higher-rate debt, or a renovation that adds more resale value than it costs. If neither applies, a plain rate-and-term refi is usually the cheaper path.
We run the break-even and show you the numbers before you apply.
Divorce & Inheritance Buyouts
Keep The House.
Buy Out The Other Owner.
Who it's for: Divorcing spouses, siblings settling an estate, or co-owners who need one person to stay in the home while the other cashes out their share. This is a financial decision made in a difficult season, so we keep every step written down and easy to review.
What usually goes wrong: The buyout gets priced from emotion instead of a documented value, one owner is left on the mortgage after the closing, or the timeline collides with a court date. Each of those is avoidable when the valuation and the financing are mapped out before anyone signs.
Typical timeline: 30 to 45 days from a signed valuation to the closing table.
How It Works
Confirm the buyout value
We start with a clean, written valuation of the home so both parties negotiate from the same number instead of from emotion.
Structure the refinance
The new loan pays off the existing mortgage and settles the departing owner's share in a single closing, not two.
Retitle in your name
The deed is transferred to you alone and the departing owner is released from the loan, so nothing lingers on either credit file.
Why It Can Cost Less Than You Expect
- One closing instead of a sale plus a repurchase
- No listing commission, staging, or moving costs
- Your rate is locked before the settlement date is set
- Both owners leave with the same documented number
Working with an attorney or mediator? We regularly coordinate with family law counsel and can provide a written buyout outline for your file.
North Georgia
A Mountain Place Without The
Paperwork Marathon.
Second-Home Lending in North Georgia
Finance Your Mountain Getaway
A cabin in the mountains is not underwritten like a house in the suburbs. Access, acreage, wells, and septic all change the file. Here is exactly how I handle those pieces so your second home closes on time and on budget.
Where I Lend
- Fannin County: Blue Ridge, McCaysville, Mineral Bluff
- Gilmer County: Ellijay, Cherry Log, East Ellijay
- Union County: Blairsville, Suches
- Towns County: Hiawassee, Young Harris
- Rabun County: Clayton, Sky Valley, Lakemont
- Dawson, White, and Habersham counties
What Usually Goes Wrong
Most delays on mountain files come from four places: an appraiser who does not know gravel-road and long-driveway comps, a survey that was never ordered, well and septic documents that surface late, and acreage plus outbuildings that push the loan outside standard guidelines. Any one of those can stall a closing by weeks.
How I Fix It
- I confirm road access, utilities, and easements before we order the appraisal
- I use appraisers who already work gravel roads and mountain acreage
- Survey, well, and septic documents get reviewed in week one, not week five
- The loan is structured up front so land size and outbuildings never surprise you
The Rule to Know
A second home stays a second home only if you occupy it yourself for part of each year. Once the cabin is rented most nights of the season, lenders treat it as investment property, and the program, pricing, and paperwork all change. Decide which one it is before we lock anything in.
Blue Ridge to Clayton and every ridge in between.
One call. We run the numbers together, no pressure.
DSCR LOANS FOR INVESTORS
Qualify On Rent,
Not Your Tax Returns.
Who It's For
Seasoned investors buying rental property inside an LLC, corporation, or trust, where the property's rent carries the file instead of a W-2.
What Usually Goes Wrong
Conventional underwriting wants two years of returns, then counts depreciation, write-offs, and K-1 income against you. Strong assets stall at the underwriter's desk and the deal dies in inspection.
How DSCR Fixes It
We underwrite the asset, not your return. Divide gross monthly rent by the full PITIA payment: at a ratio of 1.00 or better the property pays for itself, and the file moves on those numbers alone.
| Term | Detail |
|---|---|
| Income documents | Not required. Rent roll and lease terms only. |
| Minimum credit | 620 mid-score |
| Loan-to-value | 80% purchase, 75% cash-out refinance |
| Vesting | LLC, corporation, trust, or individual |
| Short-term rentals | Eligible. Market or actual STR income used |
| Where it's decided | The property's rent versus its PITIA payment |
Send me a deal: the address, purchase price, estimated monthly rent, and your mid-score. You get a term sheet back within one business day.
No tax returns. No W-2s. Just the property's numbers.
Compare at a glance
All Six Solutions On One Screen.
| Solution | Best for | Qualifies mainly on | The one thing to know |
|---|---|---|---|
| Home Purchase Loan | First-time buyers and move-up families buying a primary residence. | Documented W-2 or self-employed income, credit score, and debt-to-income ratio. | Full income documentation is required, so gather your paperwork before you start shopping. |
| Refinance | Homeowners who want a lower rate, a shorter term, or access to existing equity. | Current equity position, credit profile, and payment history on the existing loan. | Refinancing restarts the clock, so weigh the break-even month against the monthly savings. |
| Buyout Refinance | Divorcing or co-owning parties who need one name removed from the loan and title. | One borrower's ability to carry the full remaining balance without the co-owner's income. | The buyout and the title transfer have to be sequenced together, not handled months apart. |
| Second Home Loan | Buyers adding a mountain or vacation property while keeping a primary residence. | Cash reserves after closing and income that supports both housing payments at once. | Second-home pricing holds only while the property stays personal use rather than a rental. |
| DSCR Investor Loan | Investors buying or refinancing a property that will be rented out. | The rent the property commands against its mortgage payment, not personal income. | Lenders want a DSCR at or above 1.0, so the rent roll drives the entire file. |
| Clear to Close Plan | Buyers on a tight timeline who need certainty before they write an offer. | A full upfront documentation review and underwrite completed ahead of the offer. | It front-loads the work so your offer arrives with the weight of a cash buyer behind it. |
Figures, terms, and eligibility vary by lender and program. Your scenario review confirms which of these six paths are open to you.
Disclosure
Teala Smith, Mortgage Banker, NMLS #1961007. Ameris Bank, NMLS #408099. Equal Housing Lender.
All loans are subject to credit approval. This website is not a commitment to lend. [Insert Ameris's standard disclaimer.]
*Average time from [application] to closing for [loan types] closed between [dates]. Your timeline may be different.
DSCR loans are for investment properties bought for business purposes only. Program terms can change without notice.
Contact
1850 Parkway Pl, Suite 400
Marietta, GA 30067
Teala Smith
Clear from start to close.
Mortgage Banker with Ameris Bank
Marietta, Georgia


© Copyright 2026. Teala Smith. All rights reserved.
Privacy Policy
Terms and Conditions